Author: Zhou, ChainCatcher
For E-guards, the past year has been especially tough.
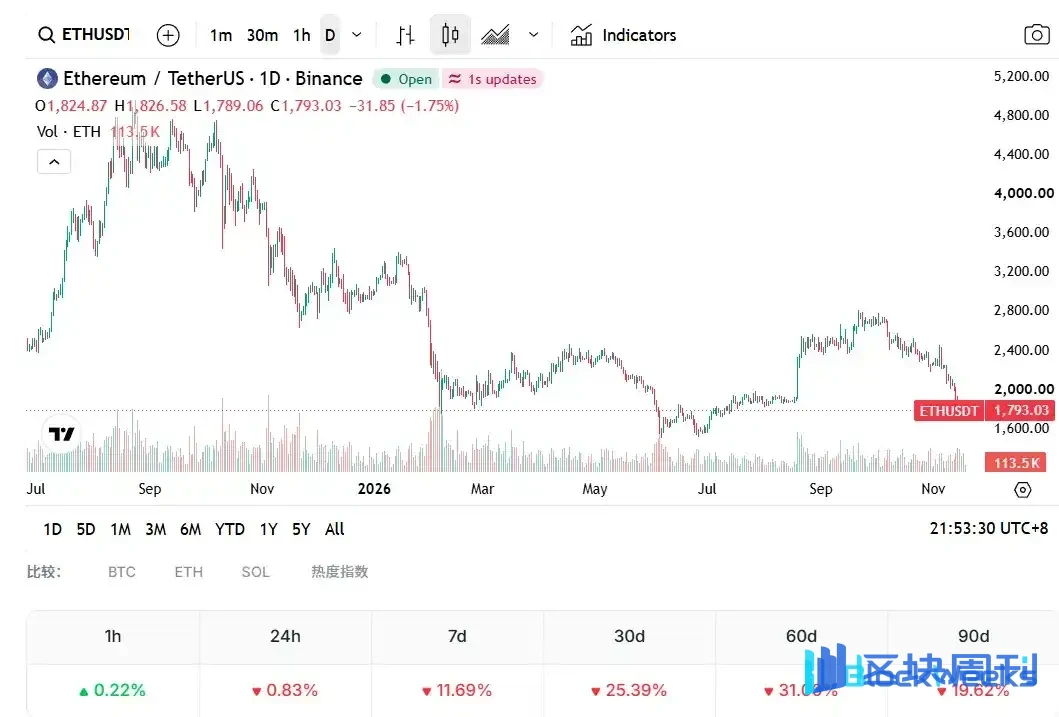
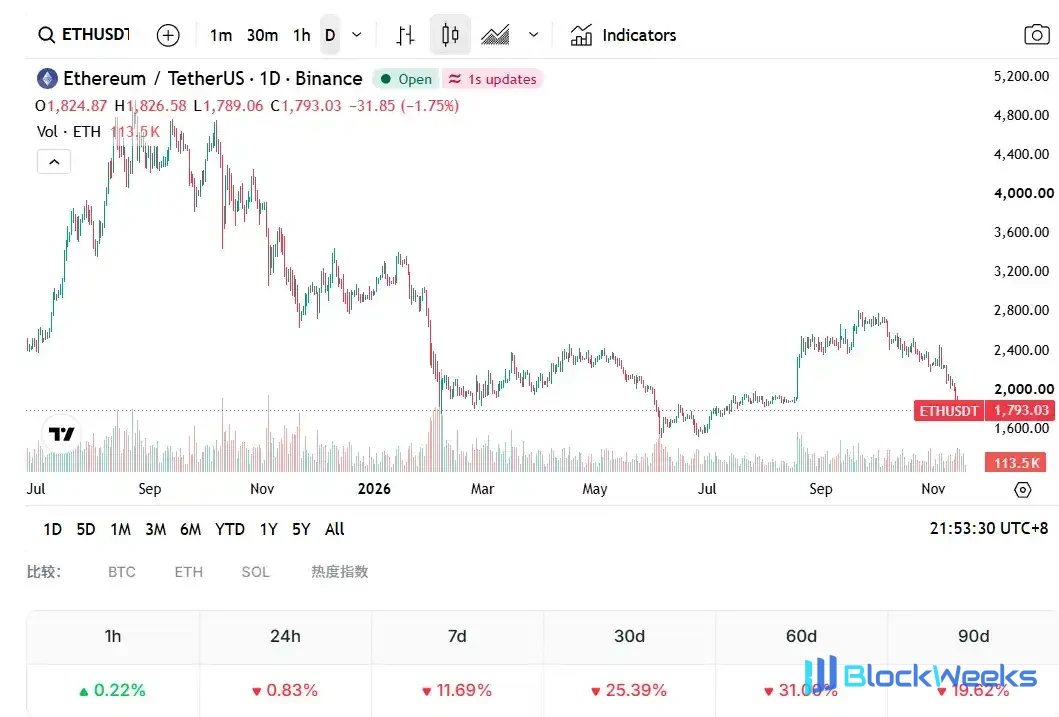
Since hitting an all-time high of $4,954 last year, the ETH price has been declining steadily. This year, ETH has repeatedly fallen below the $2,000 mark, briefly dropping below $1,600 in June, and is currently hovering around $1,800, a drawdown of more than 60% from its all-time high.
The hardest hit is Bitmine, led by Tom Lee. As of November 8, the company held 6,070,092 ETH at an average cost of about $3,353, with unrealized losses at one point approaching $10 billion.
More than a year ago, this co-founder of Fundstrat, in his capacity as a Wall Street strategist, championed ETH and was regarded as a rare institutional spokesperson for Ethereum.
Since then, no matter how the market has moved, he has almost always been able to offer bullish reasons. At the end of October this year, he still said that ETH could reach about $62,000 in the next cycle.
In the eyes of the market, his statements increasingly resemble a kind of "mindless bullishness." For a long who has seen his position nearly halved and unrealized losses approach $10 billion, how much are his words still worth?
1. Why Can't Tom Lee Move ETH Anymore?
The second half of last year was when Tom Lee's influence was at its peak. Bitmine continued to issue shares at a premium to buy coins, becoming the world's largest ETH treasury company in just a few months. Several of Tom Lee's short-term calls also came true one after another, and he was once hailed as the Pump King of ETH.
After ETH peaked and fell back in August, his bullish tone did not change. At Binance Blockchain Week in early December, he still said that ETH at $3,000 was severely undervalued and predicted that BTC and ETH would hit new highs in January 2026.
Half a month later, an internal report shattered this image. On December 20, Sean Farrell, head of digital asset strategy at Fundstrat, in a 2026 outlook for paying subscribers, took a significant drawdown in the first half of the year as the base case, giving an ETH target range of $1,800 to $2,000 and BTC of $60,000 to $65,000.
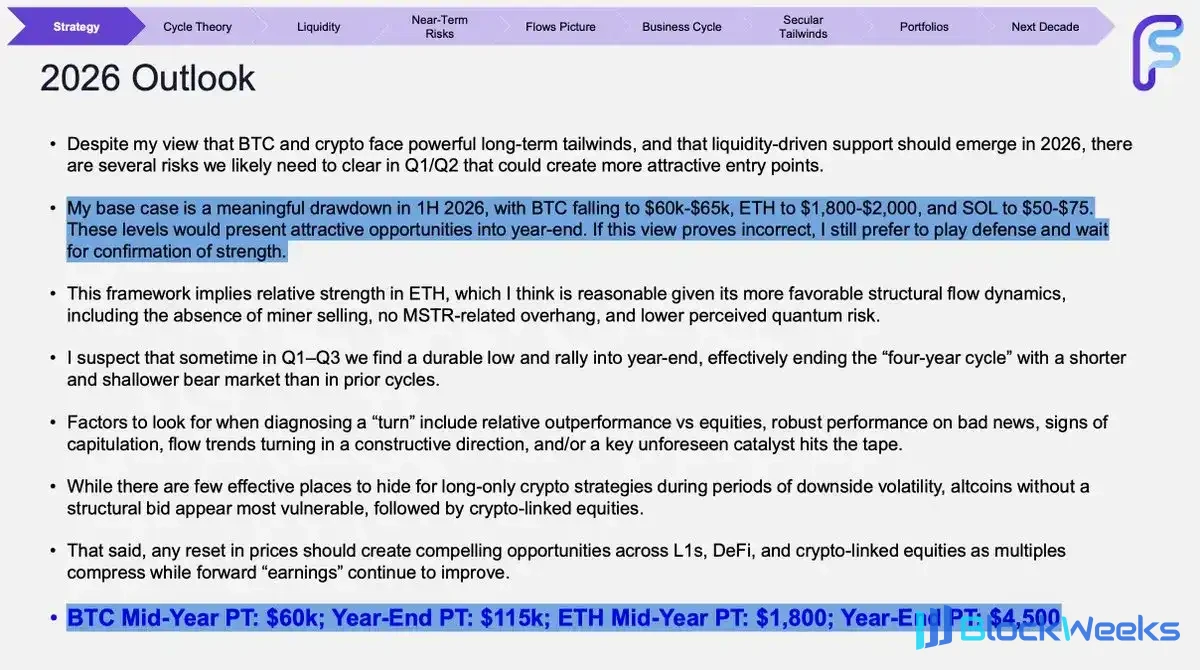
Bullish in public, bearish internally—this contrast plunged Tom Lee and his team into a trust crisis, and many saw it as the beginning of the collapse of Tom Lee's persona.
Sean Farrell later clarified that the report emphasized risk management and did not represent a bearish view. Tom Lee explained that the two stemmed from different methodologies and time horizons.
The subsequent market action largely matched the judgment of that internal report. In January 2026, neither BTC nor ETH hit new highs, and ETH has since fallen below $2,000 multiple times, even dropping below $1,600 in June.
Since September 2025, he has repeatedly suggested that ETH could reach about $62,000. By his calculation, if Ethereum replaces payment and banking infrastructure, the ETH/BTC ratio could rise to about 0.25; with BTC at $250,000, ETH would be about $62,000.
After that, he added historical cycle evidence, saying that Ethereum had risen 50 to 200 times in previous cycles, and that even a conservative estimate of 25 times would reach this price level.
As for ETH's decline, in Bitmine's weekly report on November 16, he described ETH's 28% drop over two weeks as a waterfall decline inconsistent with fundamentals, possibly due to external factors such as Nvidia dynamics and investors raising cash for Anthropic's IPO. A year earlier, the reason he gave was damage to market makers' balance sheets.

Beyond credibility, Bitmine's own situation is also weakening Tom Lee's say. The share-issuance-for-coin-purchase model that supported its expansion last year is now difficult to sustain.
As ETH fell, the company's stock price remained below the value of its holdings for a long time, and continued issuance would only dilute shareholders, so Bitmine turned to share buybacks. According to Bitmine's disclosures, as of late October 2026, the company had repurchased about 22.9 million shares for about $400 million.
In the past two weeks, Bitmine bought 9,587 and 7,653 ETH respectively; the latter is about $14 million at current prices, a clear contraction in the scale of accumulation. The company has now completed 99% of its 5% holding target and has not disclosed its plan after reaching it; it is very likely that it will no longer buy ETH afterward.
More importantly, Bitmine's scarcity as a bridge between Wall Street and ETH is disappearing. In January this year, Grayscale completed the first U.S. spot ETH ETF staking reward distribution, and in March BlackRock launched a staking ETH ETF, allowing institutions to gain ETH exposure and staking yield directly through ETFs.
At present, Bitmine basically has no debt, about 86% of its ETH is staked, and annualized staking income is about $245 million, so there is no pressure of forced liquidation in the short term. Although Tom Lee's persona has not completely collapsed, his words no longer have the same impact on the market as before.
2. After the ETH Burn Narrative Fails, Can Store of Value Convince Anyone?
Looking back at Tom Lee's bullish logic over the past year, what he talked about most was the tokenization supercycle. In his view, tokenization is making steady progress, and most of it is happening on Ethereum.
In terms of usage, tokenization is indeed happening. According to a Binance Research report, Ethereum network usage grew by about 50% in the first half of 2026, but because Gas fees continued to fall, full-year network revenue is expected to decline by 53%.
The chain is getting busier, but value is not returning to ETH. Since the shift to proof of stake, ETH has fallen more than 60% relative to BTC.
The burn logic that previously supported ETH's valuation has also failed. With the advancement of L2 scaling and a sharp drop in mainnet fees, the burn amount is far behind new issuance.
According to ultrasound.money data, calculated over the most recent 30 days, ETH's annualized burn is about 35,000 coins, annualized issuance is about 1.09 million coins, and the annual supply growth rate is about 0.86%. Since the Merge, ETH's net supply has increased by about 1.7 million coins, and the expectation of deflation has completely fallen through.

Bitcoin's ability to occupy the position of digital gold largely lies in the fact that it has barely changed its rules for years, whereas Ethereum is still in the midst of rapid iteration.
On November 8, Vitalik published an article re-emphasizing ETH's positioning as a store of value, and proposed no longer treating fee burning as the core valuation logic.
In his view, past burning mainly came from speculative demand within the crypto circle and did not constitute a true price floor; pursuing high burn amounts would also conflict with the goals of decentralization and anti-capture, and even if burning remains below one-tenth of the break-even level for a long time, there is no need to regret it.
Tom Lee, as always, added Vitalik's confirmation that ETH is a store of value to his list of bullish reasons.
Institutional investors see things differently. According to estimates by Arca Chief Investment Officer Jeff Dorman, Ethereum's roughly $6 million in monthly revenue, plus the ETH in wallets used to pay Gas, can only explain $45 billion to $50 billion of its roughly $246 billion market cap, with the rest coming more from social value and market imagination.
Crypto KOL Lanhu also believes that it is too early to talk about store of value now; Ethereum should first collect a reasonable 10% to 20% fee from L2s and block builders, solving the value capture problem at the mechanism level. Store of value can only form naturally; it cannot be achieved by shouting slogans.
Vitalik mentioned that Ethereum's roadmap is relatively mature and major changes can mostly be anticipated in advance, but he also listed a long series of protocol features expected to change, including the possibility that the consensus algorithm may undergo major adjustments in the next two years.
Crypto KOL Chen Mo said that the impact of the technical roadmap on price takes a long time to show, and what is truly worth watching is whether Ethereum can continue to win over developers; burn data is secondary.
III. The Foundation Steps Back Behind the Scenes, Can Bitmine Catch It?
Ethereum may be very successful, but why ETH must be very expensive still lacks a convincing answer.
Vitalik wrote in a long post on X that if holding ETH is about chasing financial hype, then it needs a fearless leader shouting slogans on social media. This sentence carries a hint of irony, and also shows that the Foundation has no intention of playing such a role.

The Foundation's mission document released in March this year listed anti-censorship and anti-capture as core principles.
At the same time, the Foundation is going through internal turmoil. The two co-executive directors, Tomasz Stańczak and Hsiao-Wei Wang, left in February and June respectively, and board member Bastian Aue is currently in temporary charge. In June, the Foundation announced layoffs of 54 people, about 20% of total staff, and cut about 40% of its annual budget.
Recently, former Foundation head of protocol support Kayleen Fulton sued in a U.S. federal court, alleging that she and Trent Van Epps led a public letter signed by 53 people opposing controversial provisions in the mission document, and that the two were subsequently fired in April. The Foundation has not yet filed a response.
In addition, claims that the Foundation is selling off ETH have frequently appeared in the market recently, with multiple wallets tagged as Foundation-related addresses selling ETH one after another. According to monitoring by on-chain analyst Aunt Ai, since October 26, Foundation-related addresses have sold a cumulative total of about 7,785 ETH.
However, on-chain analyst Specter cautioned that the attribution tags for some wallets lack sufficient evidence; having early fund interactions with the Foundation does not mean they are still controlled by the Foundation.
In terms of scale, the direct impact of these sales on price is limited. The ETH held by the Foundation accounts for about 0.16% of total supply, and this year it has staked about 70,000 ETH, using yield to replace part of its coin sales.
But from the perspective of retail investors, Vitalik positioning ETH as a store of value while news of the Foundation selling coins keeps coming is a contrast that is shaking market confidence.
It is worth noting that the buyers in the sales publicly confirmed by the Foundation were all Bitmine. According to Foundation announcements, from March to May, the Foundation sold a total of 25,000 ETH to Bitmine through three over-the-counter transactions, at an average price between $2,043 and $2,387.
In June this year, five former senior Foundation researchers founded the nonprofit R&D organization Ethlabs, with funders including BitMine, SharpLink, and Ethereum co-founder Joe Lubin. In July, the same group of funders supported the establishment of Ethereum Institutional, focused on institutional outreach and ETH marketing.
However, the connection between the two currently remains mostly at the level of buying, selling, and funding. After Vitalik brought up store of value again, for this narrative to be accepted by Wall Street, it still needs to be translated into a valuation logic that institutions can understand.
Final Thoughts
For ETH investors, there are few parties left to count on right now. The Foundation has no intention of speaking up for the coin price, and spot ETF funds have recently seen continued outflows. Bitmine, which holds about 5% of ETH's circulating supply, is still regarded as the party currently most motivated and most capable of holding up the ETH narrative.
The problem is that Bitmine's interests do not fully align with those of retail investors. Its revenue mainly comes from staking, its stock price performance depends on asset premiums, and after its holdings approach the 5% target, the scale of additional purchases has also noticeably shrunk.
Tom Lee's pumping is already hard-pressed to move the market again. Rather than his next target price, whether Bitmine can form more direct synergy with the Foundation and find a valuation anchor for ETH that Wall Street recognizes may be more worth watching.