This article is from: Kash Razzaghi, Chief Business Officer of Circle
Compiled by Odaily Planet Daily (@OdailyChina); Translator | Azuma (@azuma_eth)
Editor's note: As the "first stock of stablecoins," Circle (CRCL) has always been a popular target when the market chases cryptocurrency concepts. But for many CRCL investors, Circle has always been accompanied by a highly controversial dispute — in order to achieve ideal distribution, most of the revenue Circle earns needs to be handed over to distribution partners such as Coinbase, Hyperliquid, and Binance — some believe this is the core factor constraining CRCL's stock price, while others believe this is a necessary move to safeguard USDC's fundamentals...
Recently, Chief Business Officer Kash Razzaghi personally published an article explaining the specific details of this expenditure and its strategic significance. As the executive directly responsible for Circle's business partnerships, Kash may be the person in the world who best understands whether Circle should spend this money.
The following is the original text by Kash, compiled by Odaily Planet Daily.
In the first half of 2026, on-chain transaction volume settled in USDC exceeded $36 trillion. Circle minted and redeemed more than $315 billion in USDC, averaging about $1.7 billion per day (including weekends and holidays).During this period, Circle spent a cumulative $819 million on USDC distribution partners and transaction-related costs.As of June, USDC accounted for about 77% of the global stablecoin transaction volume, a significant increase from 60% in the same period last year.
These data paint the underlying picture of a "digital dollar" fully put into actual production operation — trillions of dollars in settlement scale, billions of dollars in two-way conversion with fiat currency every day, and the vast majority of economic benefits returned to the partners building businesses on top of it.
Yet recently, some newcomers claim they can build a more "usable" stablecoin.Their rhetoric is the same: existing issuers retain too much economic benefit, redemption fees are high, and the new model can solve both problems at once.
This rhetoric is quite seductive, but it both distorts the real mechanism by which USDC operates today and severely underestimates the cost required to make a stablecoin truly usable.
I am responsible for Circle's commercial business, and my team is responsible for advancing various commercial partnerships and driving USDC adoption across the world's leading wallets, exchanges, banks, fintech companies, large enterprises, and payment networks. Over the years, Circle has accumulated deep experience in landing stablecoin partnerships, helping customers around the world acquire, use, and profit from USDC through a global partner network.From this perspective, I want to lay out the real facts and data so that everyone facing technology selection and ecosystem choices can judge based on substance rather than relying on one-sided rhetoric or false headlines.
First, there are three core facts that need to be stated upfront:
- For years, Circle has shared the vast majority of USDC's economic benefits with the partners driving its adoption.
- All Circle customers have always been able to redeem for free through standard banking channels, with settlement usually completed within at most two business days. In addition, customers who process fund flows through the Circle Payments Network (CPN) or build businesses on the Circle platform can now enjoy free USDC redemption capabilities that are 24/7/365 and near real-time.
- On the core metrics that truly matter to business operations, USDC is undoubtedly the most practical stablecoin on the market today. As Circle has invested more than 8 years in continuously building and investing in its underlying infrastructure, this advantage gap continues to widen.
Next, let us analyze them one by one in depth.
How are USDC's returns distributed?
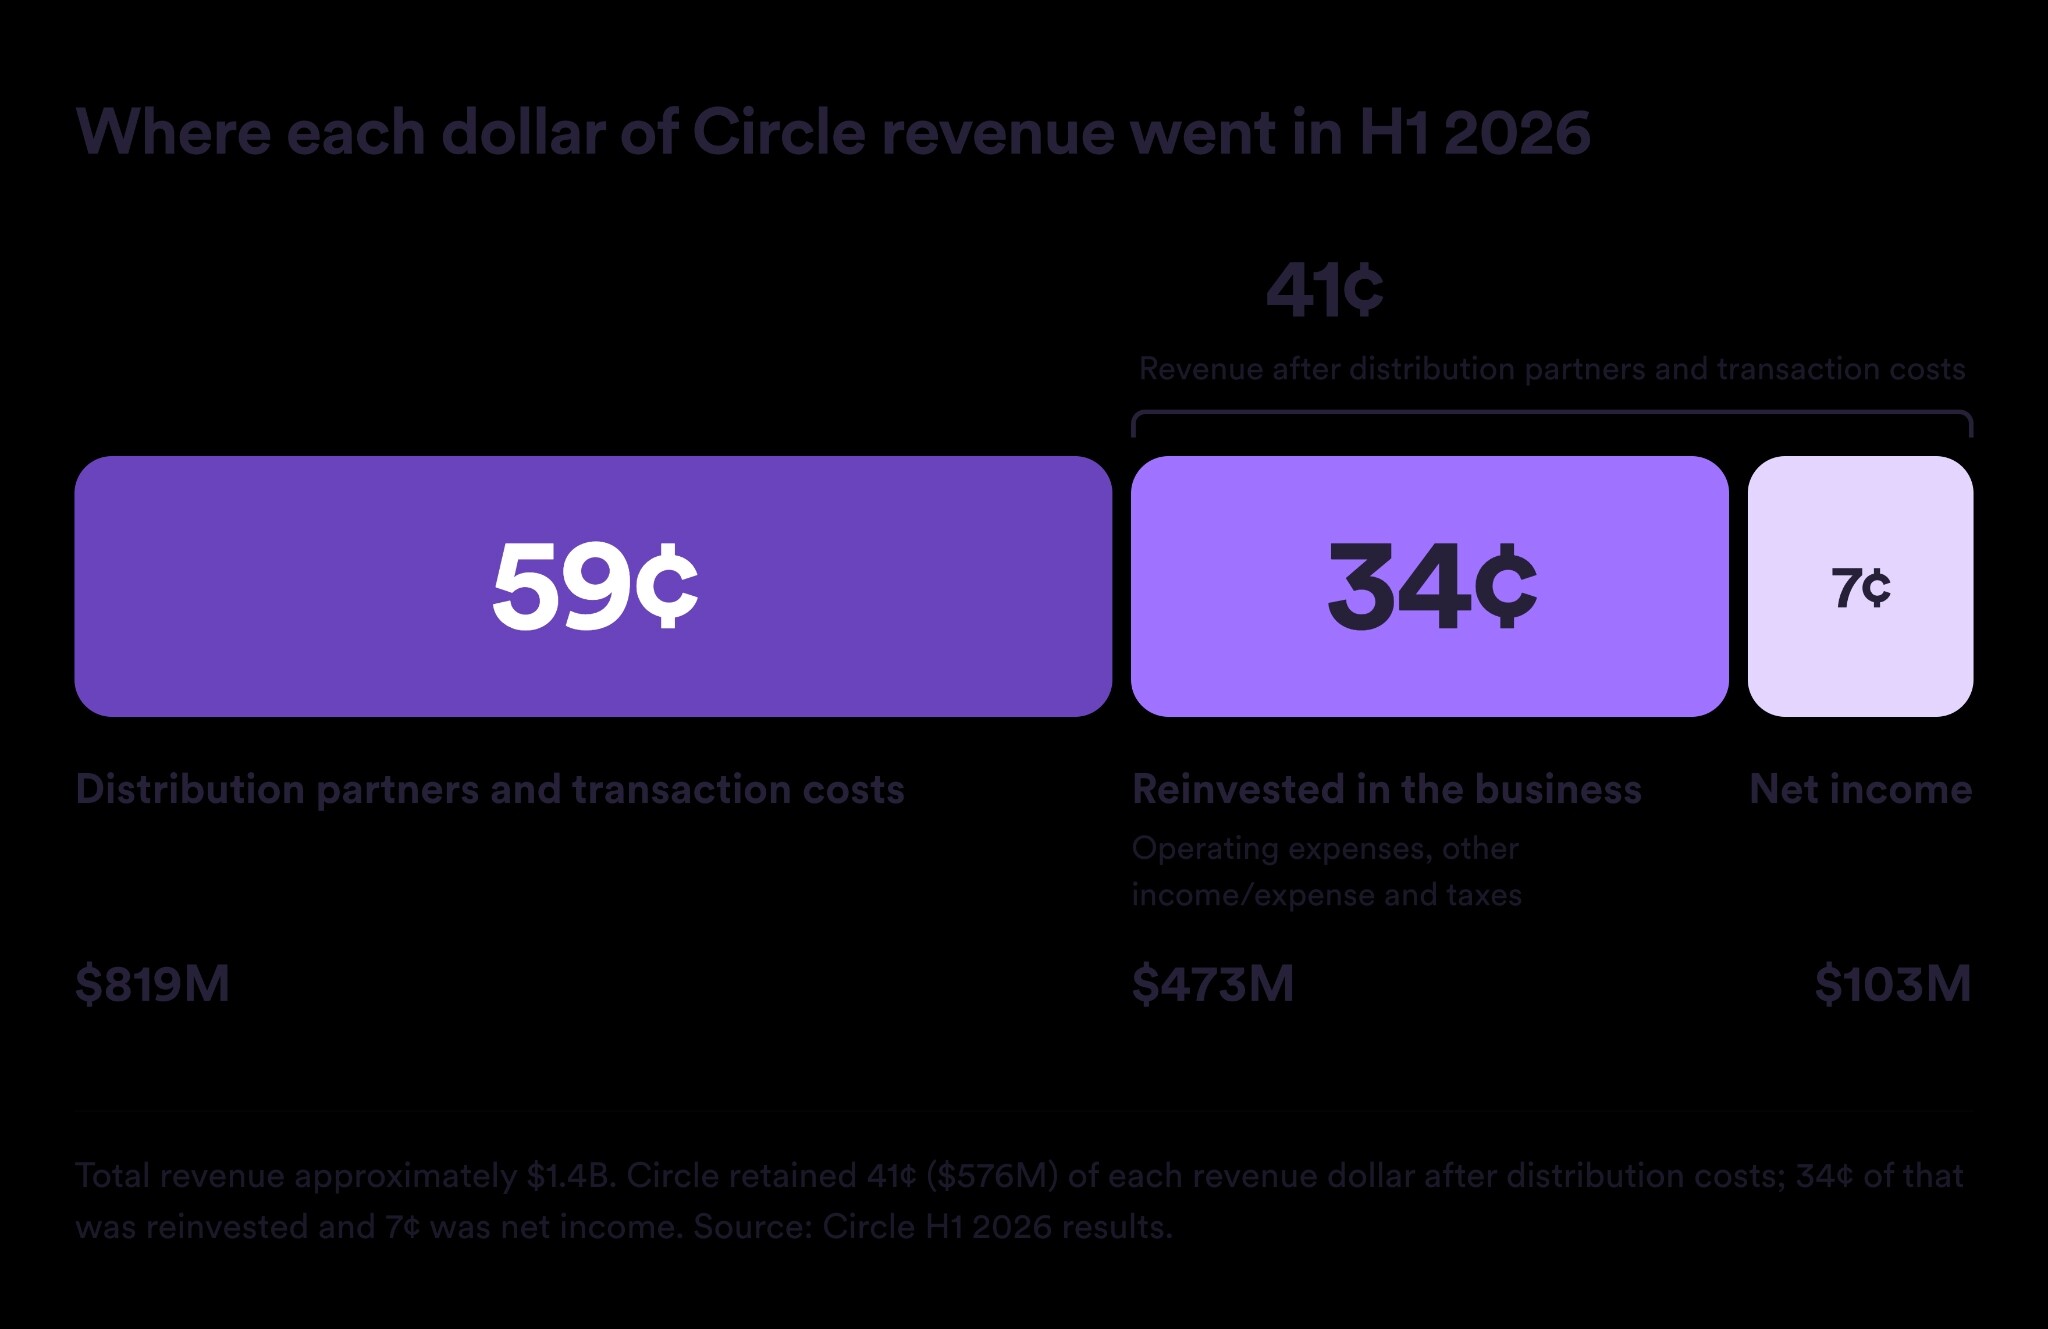
In the first half of 2026, Circle generated approximately $1.4 billion in revenue, of which about $819 million was paid to USDC distribution partners and transaction costs.This means that for every $1 of revenue, about 59 cents went directly to global partners — the very partners who popularized USDC across wallets, exchanges, banks, fintech companies, enterprises, and payment networks around the world.
Most of the remaining revenue was reinvested into building the network.Circle spent approximately $473 million (about 34 cents of every $1 of revenue) on obtaining compliance licenses, expanding banking partnerships, ensuring settlement liquidity, building compliance systems, developing new products, and advancing blockchain underlying integration.It is precisely these continuous investments that make USDC the most practical, most compliant, and most fully licensed stablecoin in the world.Of every $1 of revenue earned, Circle ultimately retains only 7 cents in net profit.
This reinvestment is by no means burdensome administrative overhead; it is precisely the cornerstone that keeps USDC highly usable, crystallizing more than 8 years of deep cultivation.A digital dollar must be usable in all scenarios and redeemable anytime and anywhere, safely held by regulated institutions, and natively circulate across the various public chains and platforms where businesses operate.
This means Circle must hold licenses in major jurisdictions around the world to ensure that banks in Europe, fintech companies in Latin America, and payment networks in the United States can all use USDC under their respective applicable regulatory rules. It also means Circle must complete native deployment on dozens of blockchains and provide cross-chain interoperability. At the same time, it also means Circle needs ample liquidity and a deep banking partnership network to support billions of dollars in daily minting and redemption needs across major financial centers around the world.
Without this foundation, a stablecoin cannot be considered a true digital dollar; at best it is merely a token. This is precisely the question that new issuers claiming to give away the "vast majority" of returns deliberately avoid — creating a stablecoin that distributes all returns away but has no ability to fund any infrastructure. Redemption costs, compliance costs, and system resilience costs do not disappear simply because an issuer refuses to bear them.For every additional $1 Circle invests, the competitive barrier grows by one more notch.
Therefore, the real disagreement has never been about "whether reserve income should be shared with the businesses building the ecosystem" — USDC's financial data has long given an affirmative answer. The real question is how to reasonably allocate and maximize shared returns while continuously injecting funds into the underlying infrastructure and ensuring the core utility of the stablecoin. This article will continue to break down: how partners participate in revenue sharing, how the redemption mechanism works, and what the actual cost of this infrastructure really is.
How partners share USDC's economic benefits
Distribution returns are directly tied to promotion results — the partners that bring the most USDC into the market also earn the most.Coinbase, as our largest and longest-standing partner, is the most representative example. In its second-quarter earnings report, Coinbase disclosed that the average scale of USDC held across its various products reached a record high of $20 billion, up 44% year over year.
But Coinbase is only one member of this vast network.In September of this year, Binance, the world's largest exchange, signed a five-year commercial agreement with Circle and invested $100 million in Circle.In addition, more than 150 partners across the entire financial system and enterprises in various industries share in USDC's growth dividends, covering exchanges, wallets, digital banks, fintech platforms, payment platforms, traditional banks, and large enterprises. It is precisely this broad foundation of participation that drove USDC to carry about 77% of global stablecoin transaction volume in June (up from 60% a year earlier).
Circle's business model is very clear, and partners mainly participate in USDC's economic benefits through two channels:
- Attract and expand capital scale, thereby earning a share of reserve income. Distribution partners who custody and accumulate USDC liquidity pools on their own platforms can earn a corresponding share of reserve interest based on the scale accumulated. The larger the USDC scale partners drive, the higher the share they receive.
- Build businesses on the platform and enjoy free instant redemption. Customers who process payment clearing through the Circle Payments Network (CPN), or build businesses using Arc, Circle Mint, and Circle Wallets, can all enjoy free near-real-time redemption. The next section will explain in detail how this works.
The Facts About Redemption
Redemption is the issue that has caused the most confusion, so I want to explain the details thoroughly. The world's leading payment networks, including Visa and Mastercard, use USDC for settlement 7 days a week, even on weekends and holidays when the traditional banking system is closed. Payment institutions around the world trust Circle's underlying capabilities to convert USDC into US dollars precisely because this system has been battle-tested at scale, around the clock, all year round.
In the first quarter of 2026 alone, Circle redeemed $71.8 billion in USDC, equivalent to about 90% of the total circulating market value at that time. In the second quarter, total minting and redemption further reached $170 billion, a year-over-year increase of 105%. No other stablecoin issuer can match this magnitude in fiat redemption processing.
Circle's redemption terms are based on three fundamental principles:
- All Circle customers can redeem USDC for free. Redemptions through standard banking channels typically settle within at most two business days.
- Payment businesses on the Circle Payments Network (CPN) can now enjoy free near-real-time settlement. Institutions that use USDC as the underlying clearing for payments on CPN—including card networks, acquirers, cross-border remittance service providers, large multinational corporations, and fintech companies processing large real volume—can now achieve zero-cost, near-real-time fund redemption. We welcome payment companies around the world to join CPN, which natively includes this capability.
- Circle platform customers can qualify for free near-real-time redemption through multiple ways. Paths include holding USDC fund balances on the Circle platform, as well as deeply integrating Circle's product matrix (including CPN, Arc, Circle Mint, Circle Wallets, and other applicable products). Eligible customers can all enjoy zero-fee near-real-time redemption.
The core support for achieving this near-real-time settlement speed is abundant liquidity. To achieve round-the-clock, unlimited, and near-real-time instant redemption (rather than waiting days), Circle has pre-positioned enormous cash lines across its global network of partner banks; once a redemption request is confirmed on-chain, funds can be immediately disbursed and transferred. These funds must remain highly liquid at all times, so their yield is naturally lower than allocating to U.S. Treasuries; at the same time, they must remain available around the clock (even during weekends when the banking system is closed), which means maintaining a long-term network of banking channels capable of mobilizing funds at any time.
We bear this holding cost ourselves, sparing customers long waits.Liquidity is the highest-weighted and most costly element in the redemption model, and as long as customers actively participate in the network ecosystem, we will never charge extra for this capability.
Building a Globally Trusted Digital Dollar
Anyone evaluating and comparing different stablecoin models should look beyond surface-level yield slogans and ask deeper questions—can the issuer honor redemptions on demand at any time? Can it operate smoothly during periods of extreme market stress? Can it consistently maintain strict compliance across different jurisdictions? And can it sustainably give back to ecosystem infrastructure day after day over the long term? These are also the core questions regulators inevitably ask during review. A stablecoin is by no means just software code; it is financial monetary infrastructure, and its foundation must be rock solid.
Circle has deeply experienced this trade-off balance. USDC was initially launched in 2018 under a consortium model;in 2023, Circle fully took over its governance and reshaped its operating system around one core logic—the issuer must have the ability to continuously invest in network infrastructure. This decision greatly advanced everything that followed. Behind every USDC in circulation today lies more than 8 years of long-term engineering investment.
These accumulations include:
- More than 55 global financial licenses and registrations (including the U.S. OCC national trust bank charter and EU MiCA license compliance);
- Clearing and settlement relationships with more than 25 banks worldwide (including systemically important banks);
- Reserve assets allocated to government money market funds managed by BlackRock and custodied by BNY, with monthly independent attestation reports;
- An anti-money laundering and sanctions compliance management system covering 185 countries and regions worldwide;
- Native deployment support across more than 35 major public blockchains;
- And an abundant instant liquidity pool sufficient to smoothly handle approximately $1.7 billion in large two-way minting and redemption daily.
This is "usefulness" at industrial scale. USDC is used by mainstream payment giants as the underlying clearing layer, is increasingly included by banks in reserve asset allocation, and is regarded by developers as the default dollar for on-chain applications. The entire industry is deeply rooted here; among the participants in other recently established stablecoin alliances, more than 70% of the companies had already built their businesses on USDC. They are all partners we deeply value, and we look forward to continuing to build together with them in depth.
The Self-Driven Flywheel
USDC's operating model is essentially a continuously self-driven "flywheel," designed to achieve symbiotic win-win across the entire ecosystem. The vast majority of economic benefits are directly passed on to partners who drive market adoption, all customers can enjoy free redemption channels, and the revenue Circle retains is fully reinvested in the infrastructure foundation, keeping it firmly in the position of the world's most useful stablecoin.
Each link of the flywheel drives the next to accelerate: partners, incentivized by the sharing mechanism, actively expand USDC scale; this scale growth provides ample funding to secure more compliance licenses, thicken the liquidity cushion, and expand more public chain integrations; and a more mature and universal digital dollar, in turn, attracts more developers, real-economy enterprises, and end users to pour in, setting off the next wave of adoption.
In the more than 8 years since USDC was born, this flywheel has weathered multiple brutal bull and bear market cycles and has always operated steadily. Looking toward the next cycle, we will continue to increase investment to make it even stronger.
Across the entire chain of distribution and customer acquisition, clearing and payments, banking channels, institutional trading, and blockchain underlying infrastructure, Circle has built the industry's broadest and deepest stablecoin ecosystem moat. If you are thinking about where to build your next-generation business, we are ready to walk forward with you.